The ROI of renovation
If that kitchen needs new countertops, your roof leaks or you want to swap out a tub for a shower, the cost might seem like a major deterrent.
But if you’re a homeowner with equity in your property, a Home Equity Line of Credit (HELOC) could be just the answer. A HELOC allows you to borrow funds based on the value of your home, and it gives you plenty of time to pay it back.
Ready to explore what you can do with a HELOC? Apply now!
A HELOC could offer flexibility when you need funds for projects, and unlike a Home Equity Loan that provides a lump sum upfront, a HELOC allows you to access cash during a set period.
Called the draw period, it typically lasts five to 10 years. You can use your HELOC funds for home improvement, giving you more freedom than a traditional second mortgage or personal loan.
Using the return on investment (ROI) as a benchmark, you can examine the numbers with a critical eye to help you finalize and prioritize your home improvement goals. A look at the numbers often can help you determine whether a particular upgrade is a critical must-have or whether it can wait its turn in favor of other home improvement projects.
To help you out, we've compiled a list of some of the most sought-after remodels in the market today, along with their ROI percentages and some perspective on how those numbers have changed.
When it comes time for you to dive into your home improvement to-do list, we’re here to help you find the financing solution that makes sense for you, your family and your unique circumstances.
If you are ready to get going on home improvement projects of practically any scope, speak with one of our Loan Officers. We have many types of loan options and home equity products like a Home Equity Line of Credit to help you bring the vision of your home to reality.
Worth vs. value
Home improvement projects can be expensive and invasive, especially if you work from home. Depending on the intensity and complexity of the project, you might need to relocate the family while upgrades are underway. It can likewise take some time after all updates are complete to get back some sense of normalcy.
We mention these factors not to put you off of home upgrades but to make sure that you factor these aspects into your thinking. After all, whether upgrades add value to your home and whether they are worth it to you can be two different things.
With that in mind, there are two things you should ponder before embarking on your home’s journey of renewal. For each upgrade, consider the following:
- The total cost of the home improvement vs. the quality of life it will add
- The upgrades worth in terms of the value it will add to your home
Ultimately, whether a particular home improvement project is worth the cost and interruption is highly subjective. There's nothing wrong with completing an upgrade simply because you want it or because it brings you joy. The list we’ve prepared with the ROI numbers is simply to give you examples so you can get an at-a-glance view into how much popular upgrades can contribute, on average, to the value of your home.
ROI numbers
ROI for home improvments is measured by how much of the cost of a particular makeover is recouped once the house is sold relative to how much it costs overall. The ROI numbers presented here are national averages. These can vary from region to region depending on a number of factors, so bear that in mind and categorize them as estimates.
Here is Remodeling magazine’s annual release of its Cost vs. Value report.1 It includes relative ROI rates for some of the most popular home improvements in 2025, the latest year for which full data is available.
HVAC conversion/electrification
- Cost: $19,484
- Value added: $14,053
- ROI: 72%
Our first item on this list is one that in 2024 sat about 66% ROI. While there are any number of factors that could affect why converting a home’s HVAC system from fossil fuels to purely electric could change in a year, it proves that this is a popular item to consider.
Something to note, however, is that such a home improvement’s ROI is never more relevant than in the year that the house is sold. So, if you just completed this type of upgrade but don't think you'll sell your house for a few more years, don't worry too much about changes from year to year. Historically, this is one of the most reliable and sound improvements.
Garage door replacement
- Cost: $4,672
- Value added: $12,507
- ROI: 268%
Garage door replacement has skyrocketed in value since last year. In 2024, this upgrade already boasted an impressive rate of 194% value, meaning that the upgrade effectively paid for itself and then some. In 2025, the ROI was an incredible 268%.
Considering that this type of upgrade has one of the lowest costs on this list, it makes it an ideal starting place for homeowners beginning their suite of home improvements.
Manufactured stone veneer
- Cost: $11,702
- Value added: $24,328
- ROI: 208%
Another home improvement that had over a 100% ROI in the previous year, a manufactured stone veneer on the exterior of a home has continued to rise in popularity. From 153% in 2024, its ROI increased to 208%. Considering the relatively low price overall, this is another way that homeowners can dramatically spruce up the appearance of their home while increasing the property value. It also goes to show the enduring power of curb appeal to potential buyers.
Kitchen remodel
Minor kitchen remodel, midrange
• Cost: $28,458
• Value added: $32,141
• ROI: 113%
Major kitchen remodel, midrange
- Cost: $82,793
- Value added: $42,130
- ROI: 51%
Major kitchen remodel, upscale
- Cost: $164,104
- Value added: $58,561
- ROI: 38%
So far, we've covered home upgrades that have undergone radical changes, both up and down. All three kitchen remodel types, however, do show differences from 2024, though perhaps not to as great a degree.
Overall, all three increased slightly in price. That's common across the board when you factor in general inflation and other economic factors.
The midrange minor remodel was the clear ROI winner of the three, going up to 113%, a change of about 15% increase from the previous year. Both the midrange major remodel and the upscale remodel ROI numbers are lower for the effort and resources involved.
Still, the kitchen is likely the first thing a potential buyer might notice in a house without furniture. And the advantages of having a modernized and upgraded kitchen while you live in the house can seldom be overstated.
Siding replacement
Fiber cement
- Cost: $21,485
- Value added: $24,420
- ROI: 114%
Vinyl
- Cost: $17,950
- Value added: $17,313
- ROI: 97%
Curb appeal is a tried-and-true approach to hook a buyer before they set foot in the house itself. As a stone veneer is one way to increase that perceived value, siding is another way to beautify and protect the exterior of the home. Not surprisingly, both types of siding have solid ROI numbers behind them this year.
Both fiber cement and vinyl options increased in ROI from the previous year, with fiber increasing more. This would suggest that the increased durability and fire-resistance of fiber cement over vinyl is more attractive to homeowners looking to preserve their homes against the elements.
Window replacement
Vinyl
- Cost: $22,073
- Value added: $16,657
- ROI: 76%
Wood
- Cost: $26,781
- Value added: $18,764
- ROI: 70%
Here is a category that is very close in both average price and ROI to what they were a year ago. Both types of window replacement increased slightly in price and in ROI, though there wasn’t a big change for either of them.
Deck addition
Wood
- Cost: $18,264
- Value added: $17,323
- ROI: 95%
Composite
- Cost: $25,096
- Value added: $22,199
- ROI: 89%
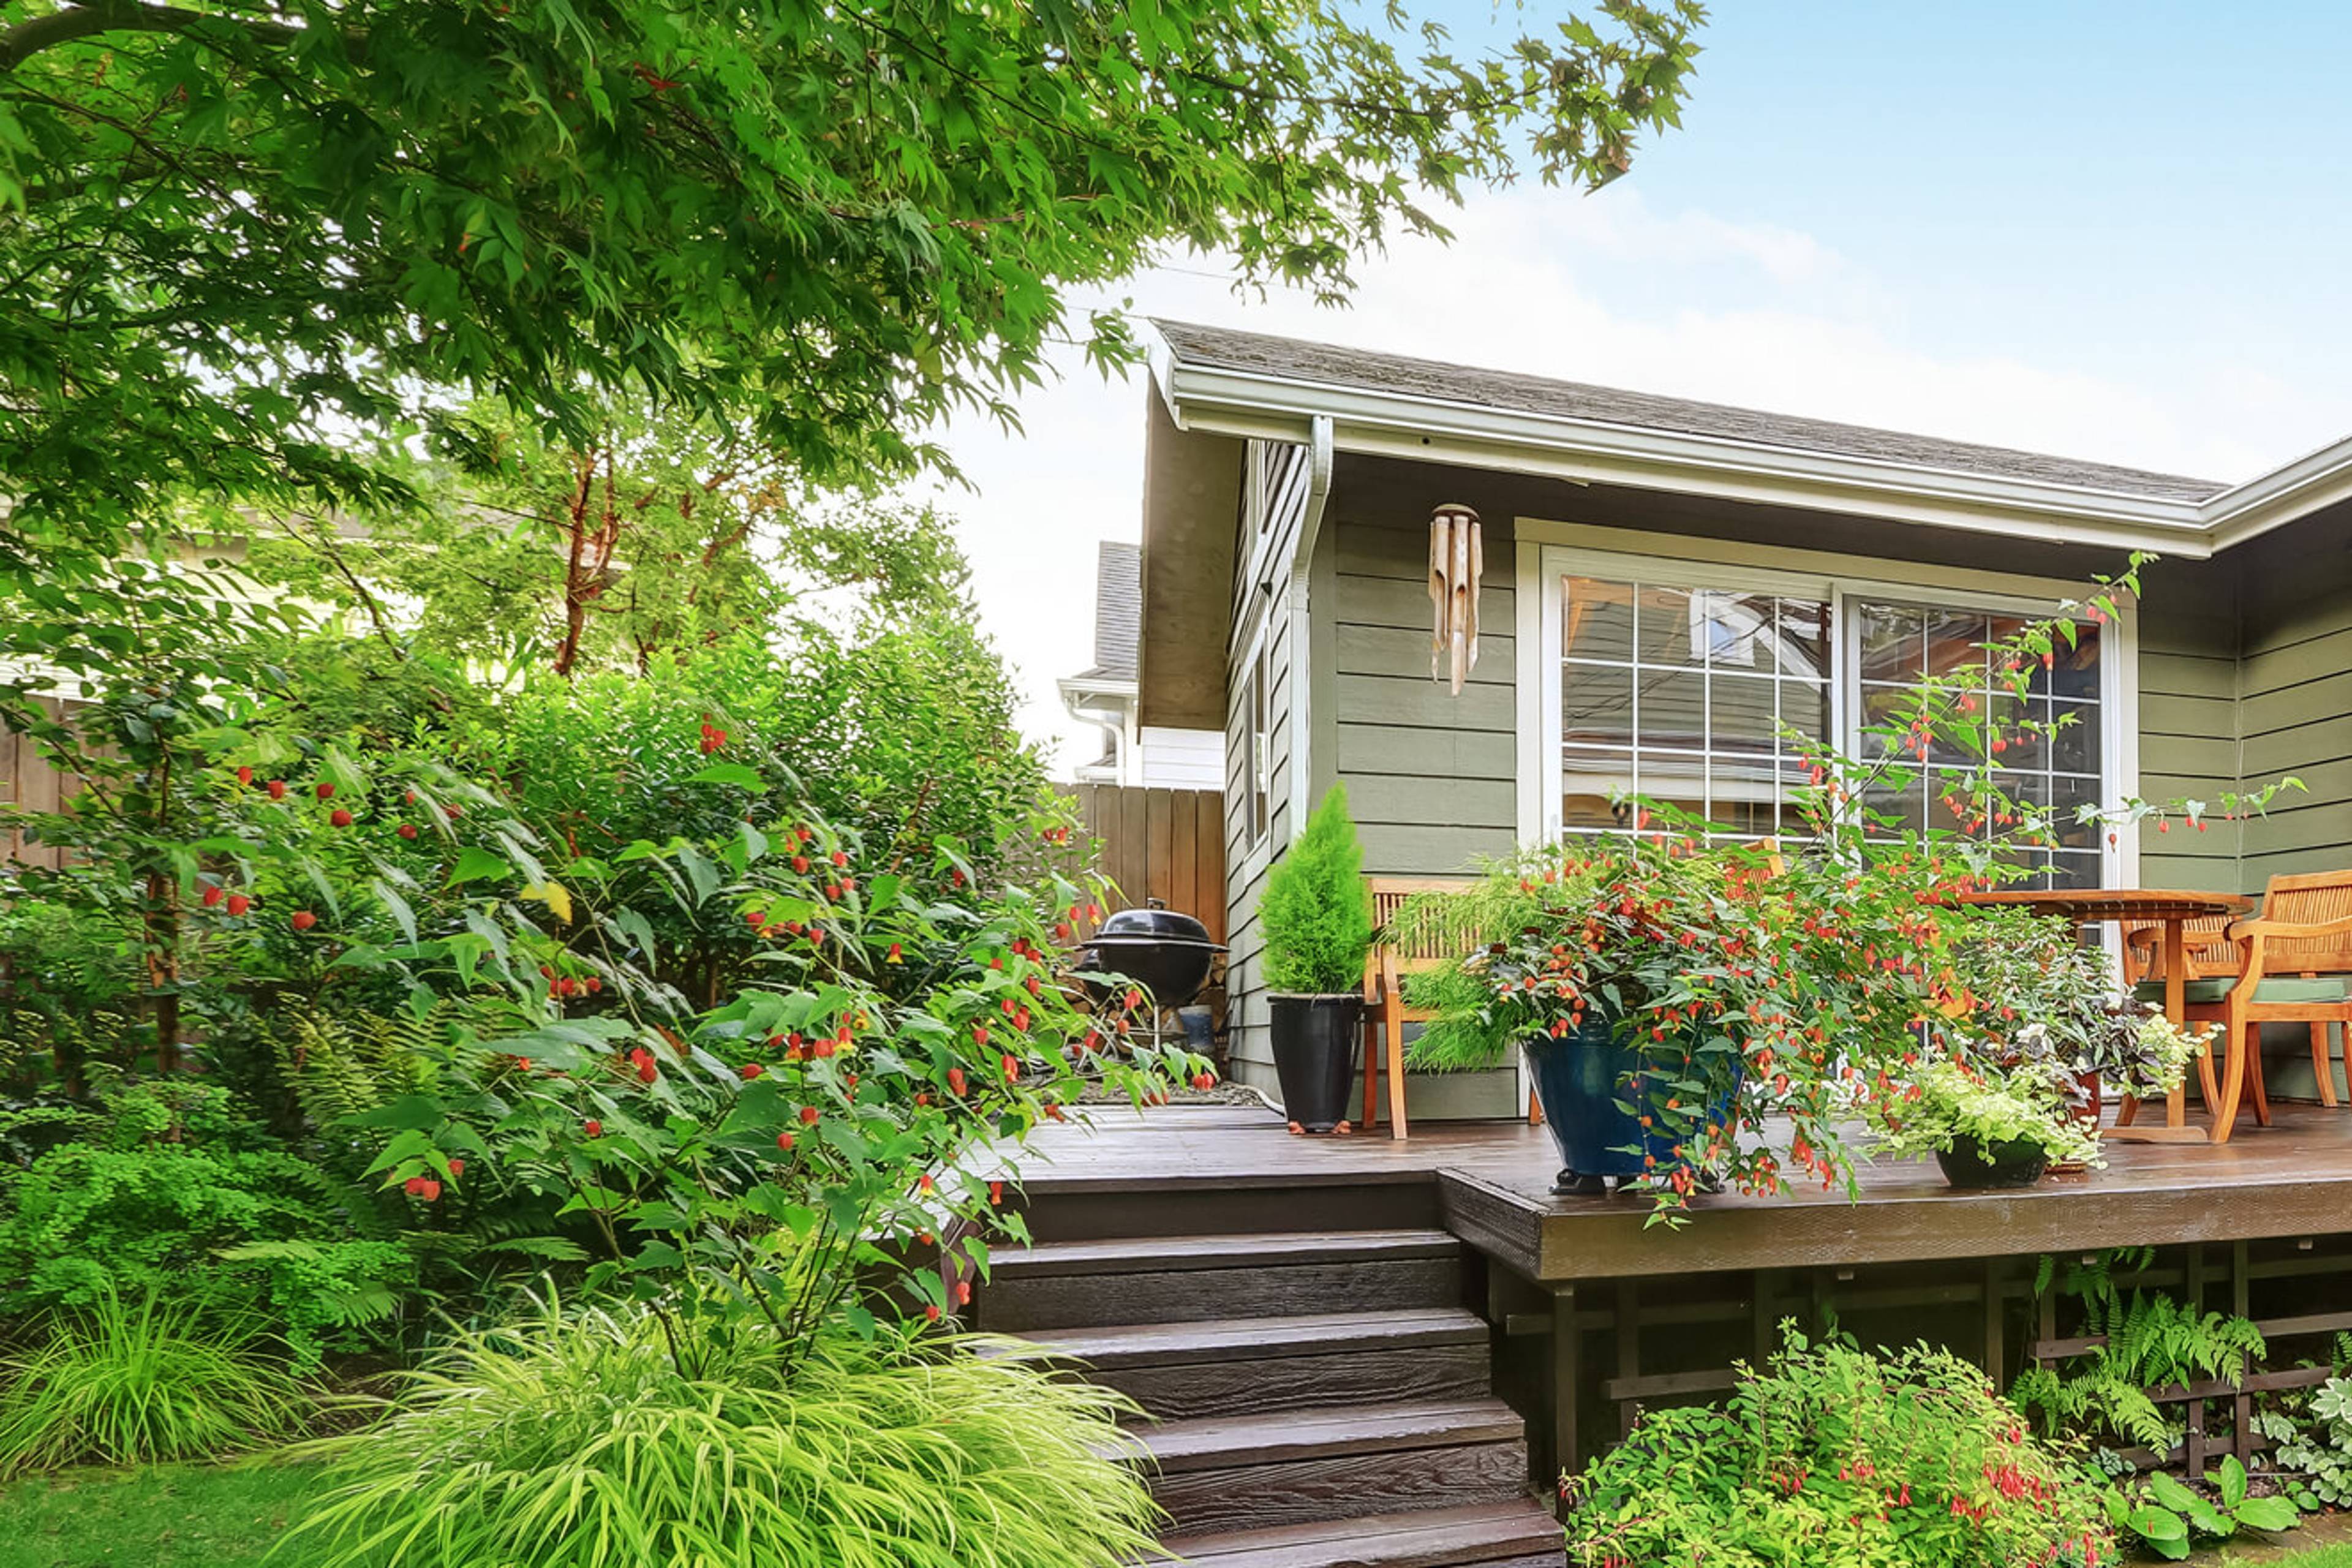
Decks have long been in-demand home features across the country, particularly in the warmer months when summer get-togethers and cookouts are popular. It seems that decks of both the wood and composite types have seen a jump in ROI numbers.
Though changing slightly in price, their return-on-investment numbers have increased. While these numbers may not be as high as other home improvement types, their increase would seem to tell the tale that the demand for decking is on the rise.
Bath remodel
Midrange
- Cost: $26,138
- Value added: $20,915
- ROI: 80%
Universal design
- Cost: $42,138
- Value added: $25,812
- ROI: 61%
Upscale
- Cost: $81,612
- Value added: $34,000
- ROI: 42%
When it comes to remodeling your bathroom, there's good news and bad news here. The good news is that overall all three levels of bathroom remodel have remained close to their price tags from the previous year. The downside is that the more upscale the remodels, the lower the ROI numbers become.
Primary suite addition
Midrange
- Cost: $170,517
- Value added: $55,097
- ROI: 32%
Upscale
- Cost: $351,613
- Value added: $63,136
- ROI: 18%
Adding or overhauling the space of the primary suite of your home can definitely be an extra draw for would-be homebuyers. Whether that takes the form of adding a new bedroom, installing a gas-powered fireplace with its own chimney, rearranging the internal configuration of your home or all of the above, you're adding features that could help your home sell quickly.
However, the high price tag of such an undertaking may not favor a return on the kind of money it takes to make such a change. In both categories, the ROI tends to be low relative to the cost. The upscale category, for example, has the lowest ROI of any on this list at just 18%, but also has the highest price of any entry here as well. So, if you plan to make such a change to your home, be prepared for it to give back only a third or quarter of what you put into it.
How to decide on a project
ROI may not be the deciding factor for you.
Some updates may be necessary, such as to accommodate the addition of a family member, whether a baby or an elderly relative. Or perhaps you just need to liven up the space to give you some quality-of-life improvements.
A Home Equity Line of Credit could be a smart way to tap into your home’s value when you need extra funds, but it’s important to borrow wisely.
A HELOC gives you access to money on an as-needed basis, often with a lower interest rate than a credit card or personal loan.
If you're ready to put your home equity to work, OriginPoint’s HELOC options make it easy to get started with competitive rates, flexible terms and a seamless application process.
1 © 2026 Hanley Wood Media Inc. Complete data from the Remodeling 2026 Cost vs. Value Report can be downloaded free at www.costvsvalue.com.
Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply.
All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. OriginPoint does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error-free. Some information in the publication may have been provided by third parties and has not necessarily been verified by OriginPoint. OriginPoint its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action. OriginPoint home equity line of credit (HELOC) is an open-end product where the full loan amount (minus the origination fee) will be 100% drawn at the time of origination. The initial amount funded at origination will be based on a fixed rate; however, this product contains an additional draw feature. As the borrower repays the balance on the line, the borrower may make additional draws during the draw period. If the borrower elects to make an additional draw, the interest rate for that draw will be set as of the date of the draw and will be based on an Index, which is the Prime Rate published in the Wall Street Journal for the calendar month preceding the date of the additional draw, plus a fixed margin. Accordingly, the fixed rate for any additional draw may be higher than the fixed rate for the initial draw. This product is currently not offered in the states of New York, Kentucky, West Virginia, Delaware and Maryland. The HELOC requires you to pledge your home as collateral, and you could lose your home if you fail to repay. Borrowers must meet minimum lender requirements in order to be eligible for financing. Available for primary, second homes and investment properties only. Dependent on minimum credit score and debt-to-income requirements. Occupancy status, lien position and credit score are all factors to determine your rate and max available loan amount. Not all applicants will be approved. Applicants subject to credit and underwriting approval. Contact OriginPoint for more information and to discuss your individual circumstances. Restrictions Apply.
Your journey home begins here.
OriginPoint's Same-Day Mortgage (aka “FastTrack”) promotion offers qualified customers who provide certain required financial information/documentation to OriginPoint within 8 hours of locking a rate on a mortgage loan the opportunity to receive a loan approval within 1 business day of timely submission of documentation and does not suggest that the borrower will receive funding on the same day as their application submission. For purposes of this offer, documents provided after 1 pm local time or on a weekend or company holiday will be deemed submitted the next business day. OriginPoint cannot guarantee that a loan will be approved or that a closing will occur within a specific timeframe. OriginPoint reserves the right to revoke this approval at any time if there is a change in your financial condition or credit history which would impair your ability to repay this obligation. Read and understand your Loan Commitment before waiving any mortgage contingencies. Borrower documentation and Intent to Proceed must be signed within 8 business hours of receipt. Not eligible for all loan types or residence types. Minimum down payment requirements apply. Self-employed borrowers and Co-borrowers are not eligible. Not all borrowers will be approved. Borrower's interest rate will depend upon the specific characteristics of borrower's loan transaction, credit profile and other criteria. Eligible borrowers who successfully provide all required documentation within 8 business hours will receive a $250 Closing Cost Credit applied at closing, no cash value, and may not be combined with any other Lender promotions, discounts, or concessions. Not available in all states. Restrictions apply. Visit OriginPoint.com/same-day-mortgage for terms and conditions.
**Eligible borrowers must qualify for a "Clear to Close Loan Commitment" ("CTC”). OriginPoint cannot guarantee that a loan will be approved or that a closing will occur within a specific timeframe. CTC is subject to certain underwriting conditions, including clear title and no loss of appraisal waiver, amongst others. Not eligible for all loan types or residence types. Minimum down payment requirements apply. Property must be eligible for an Appraisal Waiver and borrower must opt in to AccountChek for automated income and asset verification. Self-employed borrowers and Co-borrowers are not eligible. Not all borrowers will be approved. Restrictions apply.
Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Restrictions may apply, contact OriginPoint for current rates and for more information. All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. OriginPoint LLC fka Guaranteed Rate Affinity, LLC does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error free. Some information in the publication may have been provided by third parties and has not necessarily been verified by OriginPoint LLC fka Guaranteed Rate Affinity, LLC. OriginPoint LLC fka Guaranteed Rate Affinity, LLC its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action. OriginPoint does not provide tax advice. Please contact your tax adviser for any tax related questions.